Blackstone, Google-Backed Crux AI Lands $22 Billion in Chip Financing From 10 Largest Banks

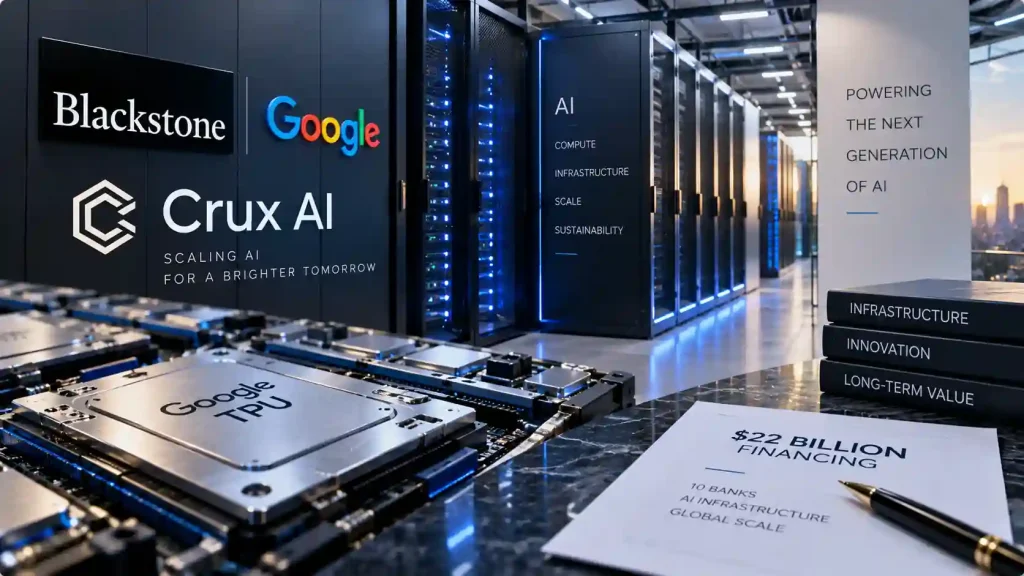
Crux AI, the artificial intelligence infrastructure venture backed by Blackstone and Google, is securing a $22 billion chip-financing package from a group of 10 banks, adding debt on top of Blackstone’s initial $5 billion equity commitment as the venture prepares to deploy industrial-scale AI computing capacity.
The financing will fund purchases of Google-designed Tensor Processing Units, or TPUs, and will be backed by the chips and Crux AI customer contracts, according to a source familiar with the transaction. Goldman Sachs, Sumitomo Mitsui Banking Corp., Barclays, BNP Paribas and Bank of Nova Scotia are among the lenders.
$27 billion capital stack emerges around Crux AI
The debt package creates an initial capital structure of roughly $27 billion when combined with Blackstone’s previously announced $5 billion equity commitment, although the debt and equity serve different purposes and should not be treated as a single financing round.
Crux AI formally launched in September after Blackstone and Google unveiled their partnership in May. The company plans to bring its first 500 megawatts of capacity online in 2027, with a broader multi-gigawatt expansion planned thereafter.
The venture’s official Crux AI platform overview describes a vertically integrated model combining power, purpose-built data centers, networking, accelerated computing, software and operations. Crux AI says it expects a capacity ramp of 2 gigawatts per year beginning in the second half of 2027.
Rather than developing data centers alone, Crux AI is positioning itself as a compute-as-a-service provider capable of supplying dedicated AI infrastructure to AI laboratories, technology companies, enterprises and governments.
Chips become collateral for mega-financings
The structure of the $22 billion loan is as significant for private markets as its size. According to the Reuters report on the Crux AI financing, the debt is being backed by both the value of Google’s TPUs and customer contracts. The bank group is also seeking additional lenders through syndication, potentially distributing the exposure across a broader institutional creditor base.
The financing could eventually be replaced with longer-term capital from investment-grade bond investors, Reuters reported, creating a potential route from bank balance sheets into institutional fixed-income markets.
That structure illustrates how AI processors are increasingly being treated as financeable infrastructure rather than simply technology equipment.
The approach resembles other large AI financings in which lenders and investors gain exposure to specialized computing assets alongside contracted cash flows from highly rated or strategically important customers.
PE NEWSWIRE previously examined the $35 billion Broadcom, Apollo and Blackstone AI infrastructure financing platform, where a special-purpose vehicle finances processors and leases computing capacity into the AI ecosystem. That transaction included senior debt benefiting from Broadcom support alongside a higher-yielding junior tranche.
Blackstone builds across the AI capital stack
Crux AI adds another component to Blackstone’s expanding AI infrastructure strategy.
The alternative asset manager has positioned itself across data centers, power infrastructure, chips and financing as the capital requirements associated with artificial intelligence move beyond traditional technology-sector investment.
The $22 billion Crux AI financing is particularly notable because it combines Blackstone’s private-market capital with the balance sheets of major global banks and Google’s proprietary computing technology.
Google will provide Crux AI with TPUs, software and services. Unlike GPUs supplied by Nvidia and other chipmakers, Google’s TPUs are custom accelerators developed specifically for machine-learning workloads.
Crux AI intends to integrate those processors with the physical infrastructure required to operate them, including power, cooling, networking and data-center capacity.
The structure effectively places Blackstone between several layers of the AI investment cycle: equity capital for the infrastructure platform, physical data-center development and large-scale financing tied to computing assets.
PE NEWSWIRE has also tracked institutional capital flowing into EQT-led AI data-center expansion through a $1.75 billion commitment from CPP Investments, another example of private-market investors allocating increasingly large amounts to the infrastructure underpinning AI workloads.
Bank syndication could broaden AI debt market
The Crux AI transaction also shows that banks remain willing to underwrite very large AI infrastructure exposures despite growing questions about the scale of capital required across the sector.
Bringing additional lenders into the syndicate would reduce individual bank exposure while potentially establishing a broader market for debt secured against processors and contracted computing revenues.
The possibility of later refinancing the facility in the investment-grade bond market is equally important. If chip-backed loans can migrate successfully from bank financing into institutional debt markets, AI infrastructure developers could gain access to a significantly larger pool of long-duration capital.
For Blackstone, that would provide another financing channel for scaling Crux AI beyond its initial 500 MW deployment.
For lenders and private-market investors, however, the structure introduces risks that differ from conventional infrastructure debt. AI processors can depreciate rapidly as new generations arrive, meaning collateral values depend partly on technological obsolescence, while the durability and credit quality of customer contracts become increasingly important to underwriting.
The $22 billion Crux AI loan, combined with Blackstone’s $5 billion equity commitment, therefore represents more than another large AI financing. It is an early test of whether specialized computing hardware and contracted AI capacity can support capital structures approaching the scale traditionally associated with major infrastructure projects.