European Pension Pressures Mount as Spain Confronts Rising Retirement Costs
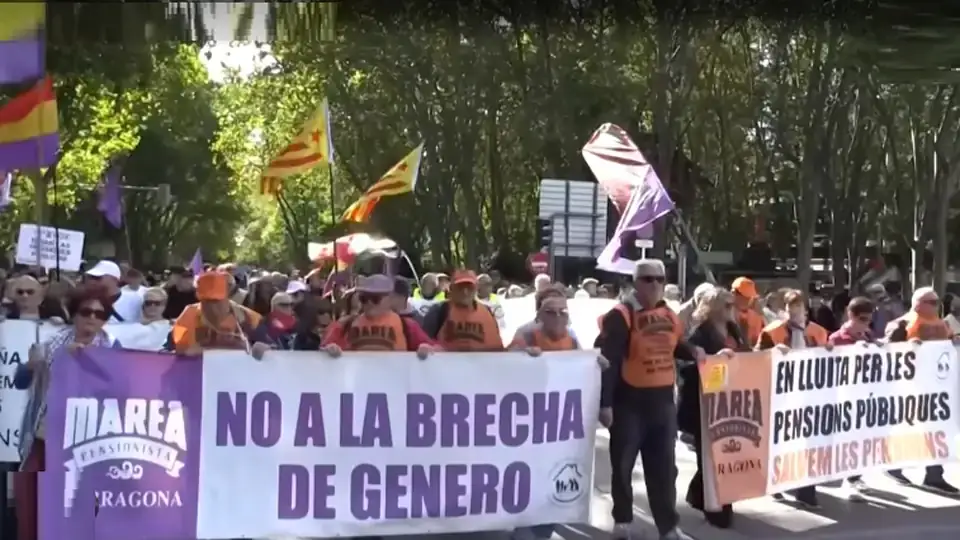
Spain’s public pension system is facing renewed political and financial scrutiny after an estimated 25,000 demonstrators marched through Madrid demanding stronger retirement protections, inflation-linked benefits and safeguards against privatization.
The demonstration comes as Spain’s monthly contributory pension expenditure has reached €14.54 billion, intensifying debate over the long-term affordability of retirement commitments in one of Europe’s largest economies. For institutional investors, the dispute raises questions about public finances, demographic pressures and the relationship between state retirement guarantees and private pension savings.
Organizers estimated that 50,000 people participated in the Madrid demonstration, compared with approximately 25,000 reported by government authorities. The protest was organized by the Coordinadora Estatal por la Defensa del Sistema Público de Pensiones, with support from trade unions and social organizations.
Spain’s Pension Expenditure Reaches €14.54 Billion
Spain’s pension financing challenge is becoming increasingly significant as its population ages and retirement benefit obligations expand.
According to the Spanish Ministry of Inclusion, Social Security and Migration’s October 2026 pension statistics, the country paid 10.57 million contributory pensions to nearly 9.6 million recipients during the month.
The average monthly pension across benefit categories reached €1,376.14, an increase of 4.6% from October 2025. The average retirement pension was €1,577.60, up 4.5% year over year.
Retirement benefits accounted for approximately €10.69 billion, or 73.5%, of the total monthly contributory pension bill.
These figures illustrate the scale of Spain’s retirement commitments, although monthly expenditure alone does not establish whether the pension system is financially sustainable. That assessment also depends on employment, contribution revenues, government transfers, economic growth and future demographic changes.
Protesters Demand Inflation Protection and Public Pension Guarantees
The Madrid demonstration focused on preserving the purchasing power of retirement benefits and maintaining the public pension system.
Protesters demanded that pensions continue to increase with inflation, that minimum retirement benefits match the statutory minimum wage and that the gender pension gap be reduced.
Trade unions also called for changes to early retirement rules, including the removal of financial penalties for certain workers with long contribution histories.
The demonstration took place ahead of Spain’s Nov. 29 general election, when retirement policy is expected to remain a contested issue.
Prime Minister Pedro Sánchez has accused the opposition People’s Party of potentially weakening inflation-linked pension increases. Opposition leader Alberto Núñez Feijóo has said his party would maintain inflation adjustments if elected.
The dispute therefore concerns not only the affordability of existing commitments but also the policy choices available to future governments.
Demographic Pressures Complicate Long-Term Pension Funding
Spain’s pension obligations are closely connected to demographic changes affecting European retirement systems.
An aging population increases the number of beneficiaries relative to the working-age population, potentially requiring higher contributions, additional public funding or adjustments to benefit structures.
The OECD’s Economic Survey of Spain 2025 estimated that age-related expenditure could increase by 5.2 percentage points of GDP through 2050, with pension costs accounting for much of the increase.
The OECD also identified inflation indexation and longer life expectancy as important factors affecting future retirement expenditure.
These projections are not forecasts of an imminent pension funding failure. They describe longer-term fiscal pressures under demographic and economic assumptions that may change.
Spain has introduced measures intended to strengthen pension financing, including additional contributions through its Intergenerational Equity Mechanism and incentives for delayed retirement.
The average age at which workers begin receiving retirement pensions reached approximately 65.4 years in 2026, compared with 64.4 years in 2019.
What the Pension Debate Means for Institutional Investors
The Madrid protests are relevant to private-market participants because public pension policy influences household retirement savings, government financing requirements and the broader environment for institutional capital allocation.
Spain’s public Social Security pension system is primarily financed through contributions and public resources. It should not be confused with funded occupational pension schemes, which accumulate investment assets and may allocate capital to private equity, infrastructure, real estate and private credit.
That distinction matters when assessing the potential investment consequences of pension reform.
Changes to public retirement benefits could influence demand for supplementary pension products over time, but the protests themselves do not establish that Spanish retirement capital will move into privately managed investment vehicles.
For alternative-asset managers, the more immediate questions concern whether future policy changes alter occupational pension participation, investment regulations or the growth of funded retirement savings.
Public pension expenditure also has implications for sovereign financing. Higher long-term fiscal commitments can affect government borrowing requirements and the interest-rate environment in which private-market investments are financed and valued.
However, no direct change to Spanish private-market allocations or institutional investment mandates has been established as a consequence of the October demonstrations.
European Protests Reflect Wider Cost-of-Living Pressures
Spain’s pension demonstration coincided with protests elsewhere in Europe, although the movements involved different political and economic demands.
Demonstrators in France protested over living costs and public services, while rallies in Italy included criticism of government policies and economic conditions.
Portugal also experienced demonstrations centered on housing affordability.
These separate movements illustrate the range of fiscal and social-policy pressures facing European governments, rather than a coordinated continent-wide campaign for pension reform.
For pension investors and asset managers, Spain’s central issue is the balance between maintaining retirement income and financing those commitments over several decades.
The next developments to monitor are the policy commitments emerging from Spain’s election, subsequent pension legislation and official projections of contribution income and expenditure.
Those decisions, rather than the demonstrations alone, will determine whether Spain’s pension debate produces material changes for retirement funding and institutional investment markets.