Global Stock Sell-Off Deepens as AI Spending Fears Rattle Wall Street, Asia and Europe

Global technology stocks suffered a sharp repricing on Nov. 5-6, 2026, as concerns about artificial intelligence investment returns and potential restrictions on U.S. data center development triggered a sell-off across Wall Street, Asia and Europe, raising new questions about valuations and financing risks for private equity, infrastructure and private credit investors.
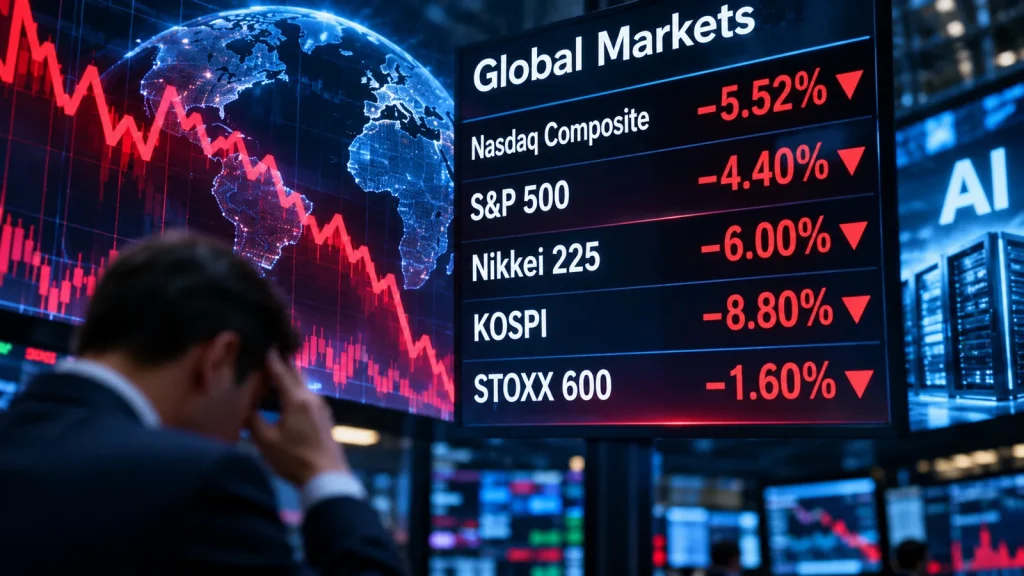
The technology-heavy Nasdaq Composite plunged 5.52% on Thursday, erasing approximately $2.5 trillion in market capitalization, while the S&P 500 declined 4.4%. Selling spread to Asian markets Friday, with Japan’s Nikkei 225 falling approximately 6% and South Korea’s Kospi dropping as much as 8.8% during trading. European equities also declined as investors reassessed the sustainability of capital spending on AI infrastructure.
The market turmoil followed Democratic victories in the Nov. 3 U.S. midterm elections, which intensified concerns about tighter oversight of data center construction, electricity consumption and the environmental impact of AI infrastructure. Those political risks compounded existing doubts about whether technology companies can generate sufficient returns on their substantial investment commitments.
For private-market investors, the immediate issue extends beyond listed technology stocks. Pension funds, infrastructure managers, buyout firms and private lenders have committed substantial capital to data centers, computing equipment, power infrastructure and AI-related businesses whose valuations depend partly on sustained investment growth.
Wall Street Sell-Off Spreads Across Three Continents
The U.S. decline was concentrated in companies closely associated with the AI investment cycle.
Nvidia, a major supplier of processors used to train and operate AI systems, fell approximately 9.3% Thursday. Advanced Micro Devices declined 17.3%, while GE Vernova, which supplies equipment used in power infrastructure, lost approximately 7.5%.
The Philadelphia Semiconductor Index dropped 12.2%, its largest one-day decline since 2020.
The Nasdaq’s fall left the index approximately 11.9% below its previous record, placing it in correction territory, commonly defined as a decline of at least 10% from a recent peak.
The sell-off extended beyond semiconductor manufacturers to companies exposed to data center construction, electricity demand and supporting technology infrastructure.
In Asia, the decline was especially pronounced among semiconductor and memory-chip manufacturers.
South Korea’s Kospi fell as much as 8.8%, triggering a 20-minute trading halt. Samsung Electronics and SK Hynix recorded substantial losses, while Japanese chip-related companies, including Tokyo Electron and Kioxia, also came under pressure.
European markets experienced smaller declines, partly because their major equity indexes have less concentrated exposure to AI-related technology companies.
The pan-European STOXX 600 declined approximately 1.6% in early Friday trading, while Germany’s DAX and other major European benchmarks moved lower.
The geographical spread of the sell-off demonstrated how closely the AI investment cycle connects U.S. technology companies with Asian semiconductor suppliers, European industrial manufacturers and global infrastructure investors.
US Midterm Elections Add Political Risk to AI Infrastructure
The Nov. 3 U.S. midterm elections introduced a new source of uncertainty for the AI investment sector.
Democrats gained control of both chambers of Congress, according to reports following the election, while several successful candidates campaigned for greater scrutiny of data center development.
Opposition to new facilities has included concerns about electricity prices, water consumption, environmental effects and the infrastructure required to accommodate energy-intensive computing operations.
Investors are now assessing whether changes in federal and state policy could delay construction approvals, increase compliance costs or restrict new projects.
The policy implications are not yet settled. Election outcomes do not automatically translate into new legislation, and the timing and scope of potential restrictions remain uncertain.
Nevertheless, the possibility of slower development has immediate financial consequences for companies whose earnings expectations depend on rapid infrastructure expansion.
A delay in data center construction can affect demand for semiconductors, electrical equipment, cooling systems, power-generation capacity and construction services.
The market reaction reflects the sensitivity of these interconnected businesses to changes in expected investment growth.
Reuters’ analysis of the global market reaction identified concerns about debt-financed AI investment, elevated valuations and potential regulatory restrictions as contributing factors.
The distinction between political uncertainty and actual policy implementation is important. A sharp equity-market decline indicates investors are reassessing expectations, but it does not establish that existing data center projects have been canceled or that financing commitments have been withdrawn.
Private Capital Faces a Test of AI Infrastructure Valuations
The market correction has implications for institutional investors financing the physical infrastructure behind artificial intelligence.
Private equity firms, infrastructure funds, pension investors and private credit managers have expanded their exposure to data centers, computing platforms and related energy infrastructure.
These investments frequently involve long construction periods, substantial upfront expenditure and financial projections based on future computing demand.
A reduction in expected AI infrastructure spending could affect valuations before individual projects experience an actual decline in revenue.
The distinction matters because private-market assets are generally valued less frequently than listed securities.
PE NEWSWIRE previously reported on CPP Investments’ $1.75 billion commitment to EQT’s AI data center expansion, which supports the development of EdgeConneX’s global digital infrastructure platform.
The investment illustrates the scale of institutional capital committed to AI infrastructure and the importance of evaluating long-term demand assumptions.
A public-market sell-off does not automatically imply a corresponding reduction in the value of established, contracted infrastructure assets.
Nevertheless, infrastructure valuations can be sensitive to changes in financing costs, expected occupancy, electricity availability and the discount rates applied to future cash flows.
Projects under construction may face different risks from operating facilities with established customers and long-term contractual revenue.
Microsoft’s SEC Filing Reveals the Underlying Investment Risks
The concerns affecting technology stocks are also reflected in corporate regulatory disclosures.
In its quarterly filing covering the period ended Sept. 30, 2026, Microsoft reported that Azure revenue increased 48% year over year, indicating continued demand for cloud infrastructure.
However, the company also acknowledged that its investments in AI and data centers require substantial capital before the associated revenue streams are fully established.
Microsoft’s September 2026 Form 10-Q filed with the Securities and Exchange Commission identified risks involving construction delays, electricity availability, regulatory approvals, infrastructure utilization and the possibility that AI demand could develop more slowly than expected.
The company warned that overestimating demand could leave infrastructure underutilized and potentially result in asset impairments.
These disclosures provide an important distinction between the expansion of AI-related revenue and the profitability of the infrastructure required to support that growth.
A company can report strong demand while still facing uncertainty about whether its capital investments will generate adequate returns.
For private credit investors financing data centers and specialized computing equipment, that distinction directly affects underwriting.
Lenders must assess the creditworthiness of contractual counterparties, the durability of cash flows and the value of collateral if demand falls short of expectations.
Private Equity and Venture Capital Face Different Exposure
The implications for private equity extend beyond infrastructure ownership.
Technology-focused buyout managers may face pressure on portfolio-company valuations if public-market trading multiples decline.
A reduction in comparable-company valuations can influence acquisition pricing, refinancing assumptions and expected exit proceeds.
Venture capital and growth equity investors face related challenges when financing companies whose valuations depend on future AI adoption.
Businesses developing AI applications may continue attracting customers even if infrastructure-related equities decline. However, investors may become more selective about revenue quality, operating margins and the capital required to reach profitability.
PE NEWSWIRE previously examined J.P. Morgan’s assessment of a $3 trillion to $5 trillion AI opportunity in private markets, including the potential for investment to expand from computing infrastructure into software and technology-enabled business services.
That distinction is increasingly relevant as investors separate the economics of developing AI infrastructure from those of deploying AI applications commercially.
The November market correction does not establish that the broader AI investment opportunity has disappeared. It indicates that investors are assigning greater importance to execution risks, financing requirements and the timing of future returns.
What Institutional Investors Should Watch Next
The November sell-off has brought three financial questions into sharper focus.
First, whether major technology companies maintain their planned capital expenditure as political scrutiny and investor pressure increase.
Second, whether data center developers can secure electricity, construction approvals and financing on terms consistent with existing investment assumptions.
Third, whether AI-related businesses can generate sufficient revenue and operating cash flow to justify the valuations attached to their expected growth.
For infrastructure investors, contracted revenue, development-stage exposure and counterparty quality will be important differentiators.
Private credit managers must assess whether borrowers can meet debt obligations if construction timelines extend or projected cash flows are delayed.
Private equity and venture capital managers face a related challenge in determining whether lower public-market valuations require adjustments to private-company pricing and exit expectations.
The Nasdaq’s 5.52% decline and the subsequent losses across Asian and European markets demonstrate how rapidly expectations can change when an investment theme becomes central to global equity valuations.
The more consequential question for private capital is whether that reassessment produces lasting changes in financing terms, transaction valuations and institutional capital commitments.
Until those changes become measurable, the November sell-off is best understood as a significant repricing of AI-related risk rather than evidence of a broad withdrawal from artificial intelligence investment.