India Weighs Capital Gains Tax Relief as Foreign Investors Withdraw More Than $50 Billion

India is facing growing pressure to reconsider capital gains taxes on foreign portfolio investors after overseas funds withdrew more than $50 billion from the country’s equity market since the beginning of 2025, intensifying concerns about valuations, currency depreciation and India’s competitiveness for international capital.
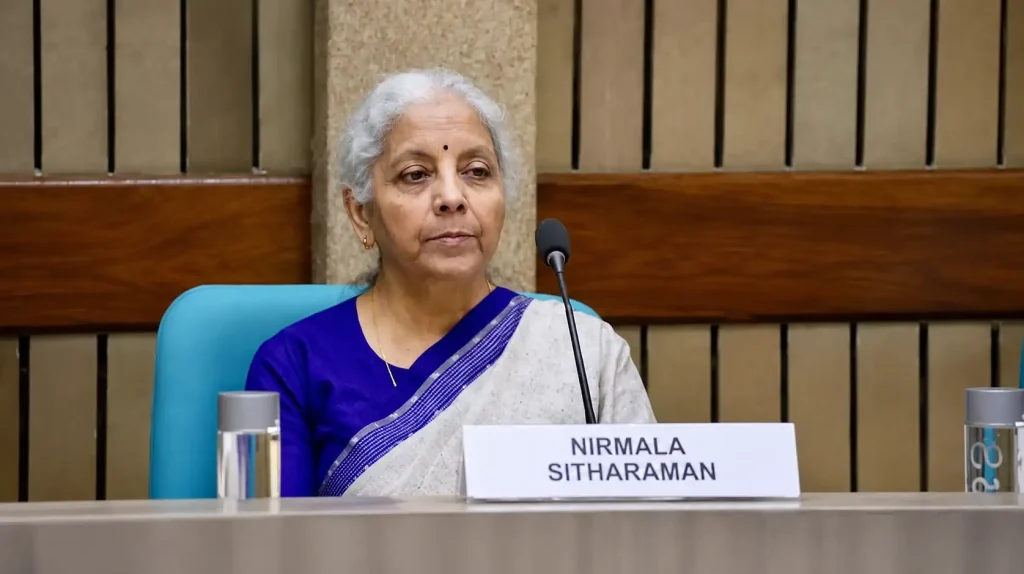
The debate has gained momentum ahead of India’s February 2027 federal budget, with market participants advocating tax exemptions to improve after-tax investment returns. Finance Minister Nirmala Sitharaman has acknowledged investor concerns but has not committed to changing the existing tax regime.
The potential changes could affect global asset managers, institutional investors and private capital firms evaluating Indian investment opportunities, although the proposals under discussion primarily concern publicly traded securities rather than private equity transactions.
Foreign Selling Raises Questions About India’s Investment Appeal
Foreign portfolio investors have reduced their exposure to Indian equities amid weaker relative market performance, elevated valuations and a depreciation of the rupee against the US dollar.
According to Bloomberg-compiled figures reported in early November, foreign investors had withdrawn more than $28 billion from Indian stocks during 2026. The broader withdrawal since 2025 exceeds $50 billion, although reported totals vary depending on the measurement date and treatment of portfolio flows.
The Securities and Exchange Board of India’s annual report provides additional perspective on the withdrawal.
In the financial year ended March 2026, foreign portfolio investors recorded net withdrawals of ₹1.53 trillion across Indian markets, reversing the ₹3.39 trillion in net inflows recorded during fiscal 2024.
Equity-specific withdrawals reached ₹1.81 trillion during fiscal 2026, while the debt market attracted net foreign investment of ₹25,807 crore.
The distinction matters because foreign selling has been concentrated in equities rather than representing an equivalent withdrawal from every Indian asset class.
Foreign ownership of Indian equities has also declined. A Nomura analysis cited by CNBC in early November placed foreign holdings at approximately 14%, reflecting a substantial reduction in international investors’ participation.
Capital Gains Tax Becomes a Policy Flashpoint
India currently imposes a 12.5% tax on qualifying long-term capital gains from listed equities held for more than 12 months. Qualifying short-term gains are generally taxed at 20%, before applicable surcharges and levies.
These rates are documented in the Indian Income Tax Department’s guidance on special capital gains tax rates.
Investors also face securities transaction taxes, while foreign investors may incur withholding taxes on dividend income.
The Securities and Exchange Board of India has reportedly recommended removing long-term capital gains tax for foreign portfolio investors as part of its pre-budget representations to the government.
Reuters reported on Nov. 2 that the regulator had also proposed tax relief for domestic mutual fund investors switching between investments. The recommendations were attributed to people familiar with the discussions and had not been publicly confirmed through a formal regulatory announcement.
Sitharaman subsequently indicated that the government would consider market participants’ concerns, while emphasizing that investment decisions depend on economic fundamentals rather than tax incentives alone.
The government also faces questions about fairness between domestic and overseas investors if preferential treatment is introduced for foreign capital.
Tax Relief May Improve Returns Without Reversing Outflows
The financial argument for reducing capital gains taxes centers on improving dollar-denominated returns for international investors.
Foreign portfolio managers evaluate Indian investments after accounting for market performance, taxation, transaction costs and exchange-rate movements.
A profitable investment in rupee terms can generate a substantially smaller dollar return when India’s currency depreciates during the holding period.
JM Financial estimated in an October analysis that eliminating capital gains tax could improve foreign investors’ average annual dollar returns by approximately 2.2 percentage points.
However, the brokerage cautioned that taxation alone would be insufficient to generate a sustained recovery in foreign investment.
Corporate earnings, equity valuations and competing opportunities in other emerging markets remain important determinants of capital allocation.
JM Financial also examined alternatives to complete tax abolition, including calculating taxable gains in dollar terms or adjusting acquisition costs to account for currency depreciation.
Such measures could address situations in which foreign investors incur Indian tax liabilities despite realizing limited gains after currency conversion.
Implications for Private Equity and Institutional Capital
Although the immediate debate focuses on foreign portfolio investment, India’s tax competitiveness has broader implications for international capital allocation.
Global private equity managers, sovereign wealth funds, pension funds and alternative asset managers frequently evaluate public and private investment opportunities within the same geographic allocation framework.
Changes to the taxation of listed securities could therefore influence how some institutions assess Indian equity exposure, particularly when comparing listed investments with private market strategies.
However, an exemption for foreign portfolio investors would not automatically extend to private equity funds, unlisted securities or investments structured through offshore holding companies.
Those investments can involve different tax provisions, treaty arrangements, ownership structures and regulatory requirements.
For private equity managers, the more direct potential connection is through exit markets.
Stronger foreign demand for listed equities could improve market liquidity and potentially support initial public offerings, which represent an important exit channel for private capital investors.
That outcome would depend on broader market conditions, including company valuations, earnings growth and investor demand. A tax reduction alone would not guarantee stronger IPO pricing or successful exits.
Domestic Investors Provide a Counterweight
India’s expanding domestic investment base has helped absorb some of the selling pressure from foreign institutions.
Mutual funds, insurance companies and pension funds have become increasingly important sources of equity capital, reducing the market’s dependence on overseas portfolio flows.
Edelweiss Financial Services Chairman and Managing Director Rashesh Shah said in a November Bloomberg Television interview that Indian mutual funds could invest approximately $40 billion to $50 billion annually in equities.
He estimated that insurers and pension funds could contribute an additional $20 billion to $25 billion, implying combined annual domestic equity inflows of roughly $60 billion to $80 billion.
These figures represent Shah’s estimates rather than confirmed future commitments.
The domestic capital base could help sustain equity issuance even during periods of foreign selling, although the composition and pricing of investor demand remain important for companies seeking to list.
February Budget Emerges as the Next Policy Test
India’s next federal budget, expected in February 2027, provides a potential opportunity for the government to address the taxation of foreign equity investors.
Any decision would require balancing capital-market competitiveness against tax revenue, fiscal priorities and the treatment of domestic investors.
The policy debate also extends beyond tax rates. The regulator’s 2025-26 annual report on foreign portfolio investment documents how international investment flows have fluctuated across financial years and between equity and debt markets.
For institutional investors, the central question is whether a change in taxation would materially improve India’s risk-adjusted investment proposition relative to other emerging markets.
Lower taxes could increase retained investment gains, but sustained foreign allocations would still depend on corporate earnings, currency stability, valuations and the availability of attractive investment opportunities.
Until the government announces a formal decision, proposals to exempt foreign investors from capital gains taxes remain under consideration rather than enacted policy.