Global Bond Yields Surge as Oil Shock Raises Private Market Financing Risks

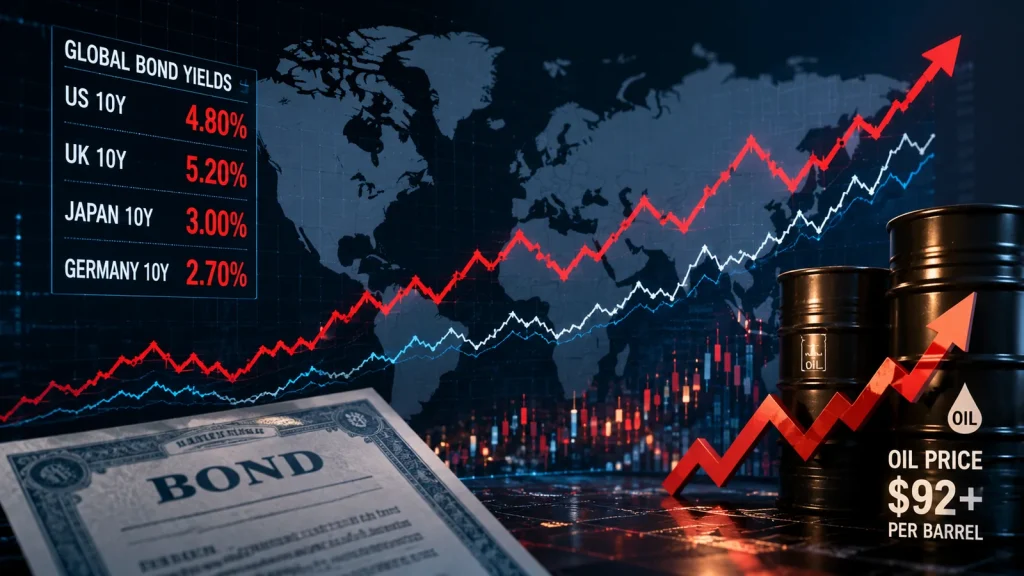
Government bond yields surged across the U.S., Europe and Asia on Sept. 1 as renewed Middle East hostilities drove oil prices above $90 a barrel, reviving inflation concerns and raising the prospect that major central banks will keep monetary policy tighter for longer.
Japan’s benchmark 10-year government bond yield reached 3% for the first time since 1996, while the U.K.’s 10-year gilt yield climbed above 5.2%, its highest since 2008. The 10-year U.S. Treasury yield touched about 4.80%, its highest since January 2025, according to market data cited by Reuters.
The renewed bond selloff matters directly to private markets because sovereign yields establish the base rate against which much corporate, leveraged and private credit financing is priced. Sustained increases can raise all-in borrowing costs, pressure leveraged-buyout underwriting and make refinancing more expensive even when credit spreads remain relatively stable.
Oil shock revives inflation risk
Energy markets provided the immediate catalyst.
Brent crude rose above $92 a barrel on Tuesday as renewed U.S.-Iran conflict increased concerns about Middle East supply disruptions. U.S. crude traded above $88.
Higher energy prices are arriving when inflation is already running above central-bank targets. Eurostat said Tuesday that euro-area annual inflation is expected to have accelerated to 3.3% in August from 2.9% in July. Energy inflation jumped to an estimated 14.3% from 10.3%.
The Eurostat August 2026 inflation flash estimate provides a particularly important signal for fixed-income investors because the energy component is now contributing substantially to renewed price pressure.
The inflation impulse complicates expectations that central banks could provide meaningful relief to borrowers through lower policy rates. Instead, bond markets are increasingly pricing the possibility that policymakers may need to maintain restrictive conditions or tighten further.
Treasury yields approach 4.8% as Fed focuses on prices
The U.S. Treasury market is particularly important for private capital because dollar-denominated financing is widely benchmarked to Treasury yields and other reference rates.
Federal Reserve Chairman Kevin Warsh said at Jackson Hole on Aug. 28 that inflation remained above the central bank’s 2% target, with 12-month PCE inflation at 3.7% and the six-month measure running at 4.1%. Warsh said the Fed’s predominant focus should currently be on prices.
The Federal Reserve chairman’s Jackson Hole remarks also noted that commodity prices warranted attention and emphasized the importance of preventing inflation expectations from becoming unanchored.
Those comments have become more consequential following the latest rise in oil prices.
The 10-year Treasury yield reached 4.798% during Tuesday trading before easing to around 4.77%, Reuters reported. A prolonged move toward 5% would increase the risk-free component embedded in valuations and financing costs across corporate credit, real estate, infrastructure and leveraged transactions.
Japan crosses a three-decade threshold
Japan produced one of the most striking moves in the global selloff.
The country’s 10-year government bond yield reached 3% for the first time since 1996, while shorter-dated Japanese borrowing costs also moved to multi-decade highs.
That shift has implications beyond Japanese government bonds. Japan has historically been an important source of comparatively inexpensive capital, while Japanese institutional investors are significant allocators to overseas bonds, private equity, infrastructure and other alternatives.
Higher domestic yields can make Japanese government securities more competitive with foreign investments on a risk-adjusted and currency-hedged basis. For private-market managers raising capital from Japanese insurers, pensions and financial institutions, that changes the opportunity cost of allocating money to long-duration illiquid funds.
It also arrives as global alternative managers continue raising large Japan-focused vehicles. PE NEWSWIRE’s recent coverage of Ares’ record Japan logistics fundraising and institutional deployment strategy would provide a direct comparison between private-market return requirements and an increasingly competitive domestic fixed-income environment.
Higher base rates pressure private credit economics
Private credit occupies an unusual position in a rising-rate environment.
Floating-rate loans can increase income for lenders when benchmark rates rise, giving private debt portfolios some protection from duration risk. But the same mechanism raises interest expense for portfolio companies and other borrowers.
That can eventually weaken interest coverage, reduce free cash flow and increase refinancing risk.
The effect becomes especially important for highly leveraged borrowers acquired when base rates and financing assumptions were lower. Sponsors contemplating exits may have to accept lower valuations if prospective buyers cannot finance acquisitions at previously assumed leverage multiples or debt costs.
Private credit managers can potentially benefit from wider spreads, stronger lender protections and increased demand from companies unable to obtain attractive syndicated financing. But those benefits depend on borrower fundamentals remaining strong enough to service higher coupons.
PE NEWSWIRE has previously examined the cost gap pushing U.S. borrowers toward bank-led loans over private credit. A renewed increase in benchmark yields raises the importance of that comparison because borrowers evaluate private credit on an all-in basis that combines the reference rate, credit spread and associated fees.
Buyout valuations face another discount-rate test
Private equity is also exposed through valuation mathematics.
Higher government bond yields raise discount rates used to value future cash flows. Unless earnings expectations improve sufficiently to compensate, higher discount rates generally reduce the present value investors can justify for an asset.
The consequences can spread through the buyout market.
Acquisition financing becomes more expensive, sponsors may need to contribute more equity to transactions, and leveraged returns can fall if debt costs rise without a corresponding increase in portfolio-company earnings.
Exit activity can also become harder. Strategic buyers and other sponsors face the same financing environment, potentially widening the gap between the prices sellers want and what buyers can economically support.
Infrastructure and real estate are particularly sensitive because many assets are valued partly on their ability to generate predictable long-duration cash flows. Higher government yields increase the return available from comparatively liquid sovereign securities, forcing private assets to offer sufficient additional returns to compensate investors for illiquidity and operational risk.
Bond supply adds to pressure
The Middle East shock is not the only force behind the selloff.
Government deficits, sovereign issuance and corporate borrowing are increasing the volume of fixed-income securities competing for investor capital. Market participants have also pointed to heavy corporate issuance associated with artificial-intelligence infrastructure investment as another source of supply pressure.
That distinction matters because an oil-price reversal would not necessarily remove the structural forces pushing yields higher.
If inflation moderates but governments continue issuing large volumes of debt, investors may still demand higher term premiums to hold long-duration securities. For private-market funds, that would mean financing conditions could remain restrictive even without another central-bank tightening cycle.
Private markets face a higher hurdle rate
The most consequential issue for private capital is therefore not Tuesday’s bond-market move in isolation, but whether the repricing persists.
Private equity, private debt, infrastructure and real estate funds compete with public markets for institutional capital. When sovereign bonds offer materially higher yields, LPs can obtain greater income without accepting the illiquidity, leverage and execution risks associated with private assets.
That raises the return threshold alternatives managers must clear.
For private credit, higher sovereign yields can produce attractive headline coupons but increase borrower stress. For private equity, they can reduce leverage capacity and valuations. For infrastructure and real estate, they can push capitalization and discount rates higher.
The Sept. 1 bond rout therefore represents another test of private markets’ adjustment to structurally higher financing costs. If the Middle East conflict keeps energy prices elevated and inflation remains above target, the anticipated path toward cheaper capital could be postponed again — extending the period in which private-market managers must generate returns with less leverage and more expensive debt.