Atlantic Coast Life Private Credit Exposure Draws State Takeover Bid

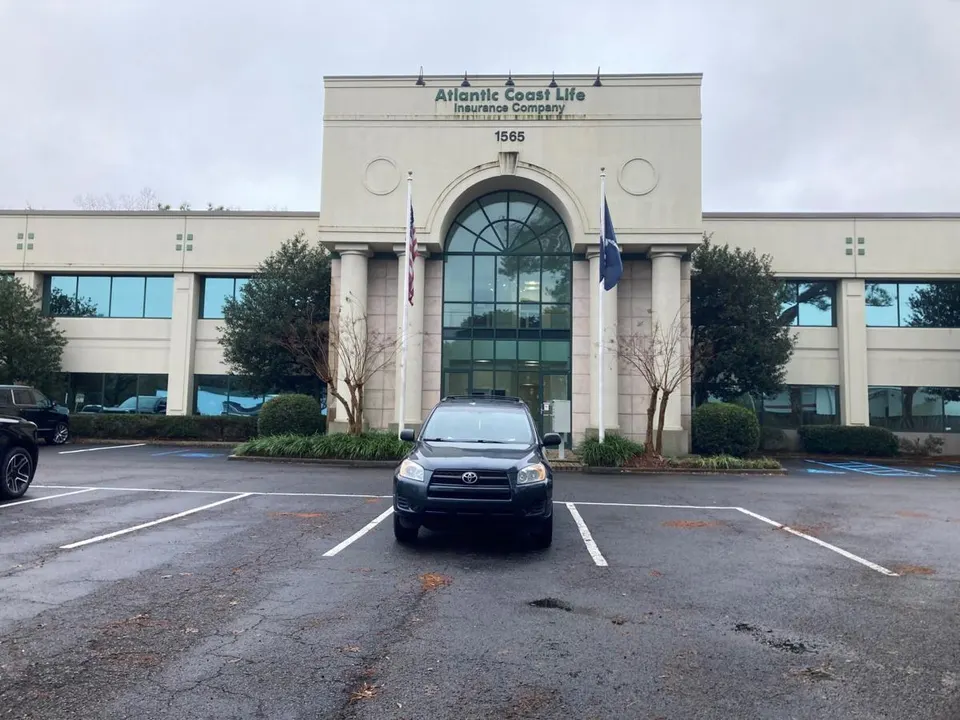
South Carolina insurance regulators are seeking court control of Atlantic Coast Life Insurance and its reinsurer Southern Atlantic Re, alleging that A-CAP exposed policyholder money to excessive amounts of sub-investment-grade private credit, unrated collateral loans and investments linked to collapsed investment firm 777 Partners.
The Sept. 15 rehabilitation petition has not been granted, and A-CAP disputes the allegations. The regulatory pressure nevertheless intensified when Florida suspended Atlantic Coast Life’s authority to write new business after determining the insurer was impaired, while requiring it to continue servicing existing policies.
The dispute provides a high-profile test of the increasingly close relationship between private capital and life insurance, where insurers can provide alternative asset managers with long-duration capital but must maintain sufficient liquidity and capital to meet policyholder obligations.
Regulators allege private credit exceeded agreed limits
South Carolina Insurance Director Michael Wise alleges that 30% of Atlantic Coast Life’s cash and invested assets at the end of 2025 consisted of sub-investment-grade private credit instruments and unrated collateral loans.
That compared with a 10% limit on private-placement holdings contained in investment-management agreements with A-CAP affiliates, according to the regulator’s petition. The 10% threshold is described as a contractual limit rather than a general statutory ceiling.
The state also alleges that tens of millions of dollars of assets classified as investment-grade bonds should instead have been reported as unrated collateral loans.
The South Carolina Department of Insurance said it is seeking rehabilitation of Atlantic Coast Life and Southern Atlantic Re so the companies’ finances can be examined under court supervision and measures considered to restore them to sound financial condition.
A rehabilitation petition is not a liquidation order, nor does filing one establish the regulator’s allegations as fact. As of Oct. 4, no rehabilitation order had been entered. A-CAP maintains that its insurers continue to meet policyholder obligations.
777 Partners exposure adds to pressure
The dispute is complicated by Atlantic Coast Life’s exposure to 777 Partners, the Miami investment group that filed for bankruptcy after financial and legal problems across its portfolio.
South Carolina’s petition points to a separate 777 bankruptcy filing indicating that A-CAP and affiliates could be owed almost $1.3 billion.
777 Partners founder Josh Wander was indicted in October 2025 on wire fraud and securities fraud charges involving an alleged scheme to defraud lenders and investors of more than $500 million. The charges concern Wander and do not establish wrongdoing by A-CAP or its executives.
A-CAP has also disputed claims that it controlled 777 Partners, describing its relationship as that of a lender with senior rights over collateral.
The distinction is important because the regulatory case against Atlantic Coast Life concerns both the credit quality of its investments and whether the insurer appropriately valued, classified and disclosed them.
For private-credit investors, the episode demonstrates how counterparty problems can become more significant when a lender has concentrated exposure to a borrower or group of related assets.
Capital falls as policyholders withdraw $463 million
The pressure is not limited to asset classifications.
Atlantic Coast Life’s capital and surplus declined 42% during the first six months of 2026, according to the South Carolina petition, while policyholders withdrew a gross $463 million of annuities.
Florida subsequently suspended Atlantic Coast Life’s certificate of authority after concluding the insurer was impaired.
The Florida regulator said Atlantic Coast reported surplus of about $47 million in the second quarter, below a required level of approximately $55 million. Applying Florida’s statutory investment limits produced an impaired-surplus calculation of about $170 million, according to the state’s order.
Atlantic Coast can no longer solicit new or renewal business in Florida while the suspension remains in force, although the insurer must continue servicing existing policies.
That distinction illustrates the central liquidity issue for insurers holding private assets: policyholder liabilities can require cash even when the underlying investments are difficult to sell quickly without accepting discounts.
AM Best cuts Atlantic Coast to C+
The deterioration has also reached the ratings market.
AM Best lowered Atlantic Coast Life and sister insurer Sentinel Security Life’s financial strength ratings to C+ from B on Sept. 22 and cut their long-term issuer credit ratings to “b-” from “bb+”.
The ratings agency cited weakening balance-sheet strength and operating performance during the first half of 2026, while maintaining both ratings under review with negative implications.
A-CAP disagreed with the downgrade, arguing that it did not fully reflect pending capital-raising and corporate restructuring initiatives.
The company and South Carolina have since agreed to mediation. Atlantic Coast Life and Southern Atlantic Re dismissed a lawsuit against Wise without prejudice as part of that process.
In its Sept. 28 regulatory update, A-CAP said it remains focused on completing capital-raising and restructuring initiatives and supporting its insurance companies as they continue meeting policyholder obligations.
Insurance becomes a major frontier for private credit
The Atlantic Coast dispute arrives as the insurance industry plays a larger role in the growth of private markets.
Private capital managers have increasingly acquired insurers, established reinsurance platforms or formed strategic partnerships with insurance companies. Insurance balance sheets can provide stable, long-duration liabilities that are well suited to investments such as corporate credit, asset-backed finance and other income-producing assets.
But the model depends heavily on asset-liability management.
Private loans can provide additional yield compared with conventional investment-grade bonds, but they may also be harder to value and sell. That creates additional complexity when insurers experience unexpected policyholder withdrawals or deteriorating credit positions.
The regulatory concerns surrounding Atlantic Coast therefore intersect with the broader scrutiny facing private credit. PE NEWSWIRE recently reported that global regulators are intensifying their focus on private-credit valuation, liquidity and leverage as the asset class expands deeper into the financial system.
The Atlantic Coast case makes those concerns tangible because the underlying liabilities belong largely to insurance and annuity customers rather than institutional limited partners capable of accepting multiyear lockups.
Oaktree transaction remains pending
Another important variable is Oaktree Capital Management.
Oaktree, the credit specialist majority-owned by Brookfield Asset Management, agreed earlier in 2026 to acquire a controlling interest in Atlantic Coast Life as part of a broader transaction with A-CAP.
The deal has not closed and remains subject to restructuring and regulatory approvals.
Its presence adds another layer to the private-capital connections around Atlantic Coast, although the pending transaction should not be characterized as a completed rescue of the insurer.
The regulatory dispute also comes as investors are paying closer attention to liquidity across private-credit structures. PE NEWSWIRE’s coverage of Blackstone’s $77 billion BCRED and its $4.3 billion of redemption requests illustrates how withdrawal pressure can become a critical consideration even outside insurance balance sheets.
The structures are fundamentally different, but the underlying issue is similar: assets designed to earn an illiquidity premium must ultimately coexist with liabilities or investor redemption mechanisms that can demand cash.
Court process will determine next step
No court has determined that Atlantic Coast Life, Southern Atlantic Re or A-CAP committed the violations alleged by South Carolina regulators.
That qualification is particularly important because A-CAP has challenged the regulator’s conclusions, says policyholder claims continue to be paid and is pursuing mediation while working on additional capital and restructuring measures.
The next significant developments include the outcome of mediation, any court decision on rehabilitation and regulatory consideration of the proposed Oaktree transaction.
For private-market investors, however, Atlantic Coast already presents a broader lesson. The expansion of private credit into insurance does not simply create another source of capital for alternative assets. It places private-credit valuation, concentration and liquidity directly inside institutions that promise policyholders future payments.
As regulators examine those connections more closely, the Atlantic Coast dispute could become an important reference point for how much illiquid private credit insurers can hold — and how quickly supervisors intervene when those assets come under stress.