Apollo Brings Daily Pricing to Its $850 Billion Platform as Private Credit Faces Transparency Test

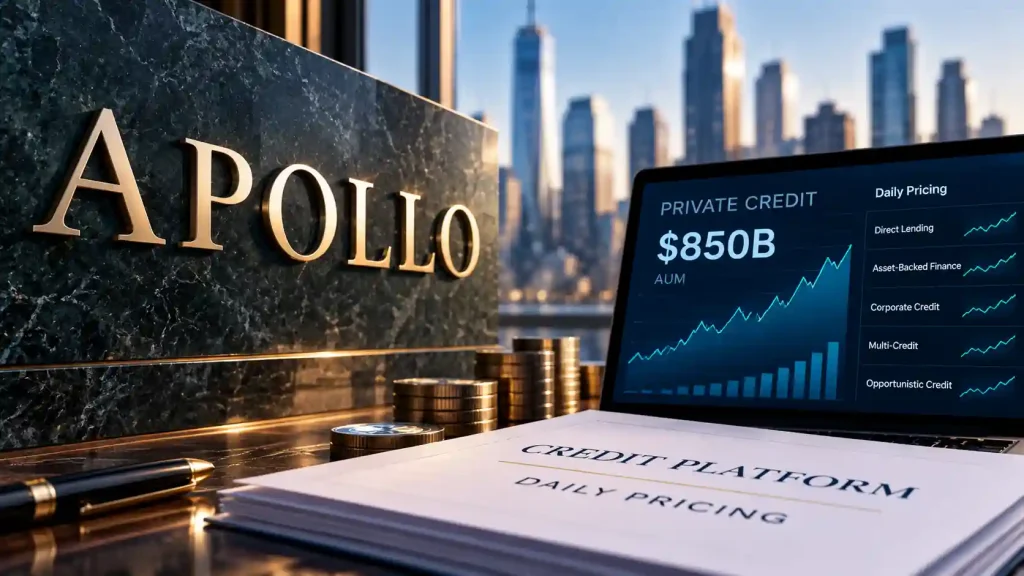
Apollo Global Management has expanded daily pricing across its roughly $850 billion credit business, bringing more frequent valuations to direct lending, asset-backed finance and other private-credit strategies as investors and regulators intensify scrutiny of how illiquid assets are valued.
The New York-based alternative asset manager began extending the pricing initiative Oct. 1 after introducing daily marks for its investment-grade Fixed Income Replacement products on July 1. Asset-level pricing for applicable funds is scheduled to become available to investors beginning Oct. 30.
The change is significant because private loans have traditionally been valued much less frequently than publicly traded bonds. Apollo is effectively trying to bring part of the data and valuation infrastructure of public fixed income into a private-credit market that has grown rapidly but remains comparatively opaque.
Daily marks reach direct lending and asset-backed finance
Apollo’s expansion covers various direct-lending, asset-backed finance, multi-credit and opportunistic-credit vehicles. Investors will receive pricing through the firm’s investor portal, while information for registered funds will be distributed through the channels applicable to those vehicles.
The manager describes Daily Pricing as an estimated fair value rather than a price at which an asset could necessarily be sold. Apollo benchmarks its internal methodology against relevant public-market information, meaning the marks should not be interpreted as executable secondary-market quotations.
That distinction matters in private credit. Loans can trade infrequently or not at all, particularly when they finance middle-market companies or specialized assets. A daily valuation therefore provides a more current estimate of economic value without creating daily liquidity in the underlying investment.
Apollo details the methodology and rollout in its official Daily Pricing expansion announcement.
The scale is substantial. Apollo reported $849 billion of credit assets under management as of June 30, 2026, supported by more than 600 investment professionals and relationships with more than 4,000 issuers, according to the firm’s credit platform disclosure.
Apollo builds infrastructure around private credit pricing
Daily marks are one part of a broader attempt by Apollo to make private credit more standardized and tradable.
The firm is working with Intercontinental Exchange to assign standardized ICE identifiers to private assets. More than 5,000 ICE IDs have been created so far, Apollo said, supporting reference data, analytics and independent pricing.
Apollo has also operated a dedicated secondary trading desk since 2024. That operation has facilitated more than $30 billion of trading volume, according to the manager.
Those initiatives address two longstanding limitations of private debt: inconsistent security-level data and limited price discovery.
Standard identifiers make it easier for investors, administrators and pricing services to track individual instruments, while secondary trading creates observable transactions that can help test model-derived valuations.
The combination does not turn private loans into public bonds. But it could narrow the infrastructure gap between the two markets.
Valuation scrutiny rises with private-credit stress
The timing is important because valuation practices are becoming a larger concern as private credit matures.
The U.S. private credit default rate reached a record 6.3% in August, according to Fitch Ratings data previously examined by PE NEWSWIRE in its coverage of rising U.S. private credit defaults.
Higher defaults make valuation methodology more consequential. When a borrower deteriorates, a privately held loan may have few recent transactions available to establish what another investor would actually pay.
That creates potential differences between manager marks, third-party valuations and prices eventually achieved through restructurings or secondary transactions.
Apollo’s daily approach could provide investors with more frequent information about how changes in rates, spreads and borrower fundamentals affect estimated portfolio values. It does not eliminate the judgment involved in valuing illiquid credit.
Transparency and liquidity are different questions
Daily pricing also arrives as perpetual private-credit vehicles face scrutiny over investor liquidity.
Blackstone’s BCRED, for example, received about $4.3 billion of third-quarter redemption requests, equivalent to roughly 10% of shares outstanding, forcing the vehicle to limit repurchases to its standard quarterly threshold. PE NEWSWIRE examined the implications in its coverage of BCRED’s private-credit redemption pressure.
Apollo’s initiative addresses a related but different problem.
More frequent marks can give investors greater visibility into portfolio values, but they do not make the loans themselves more liquid. A private-credit fund can publish a daily estimated value while still owning assets that could take weeks or months to sell at an acceptable price.
Indeed, greater pricing frequency could make volatility more visible. Private assets have historically appeared smoother partly because they are valued less frequently than publicly traded securities.
Apollo has acknowledged that its Daily Pricing is not a market-clearing price. For one of its asset-backed vehicles, the manager says the daily estimate reflects the prior business day and becomes available the following business day; it may also differ materially from GAAP net asset value or a transactional NAV.
Private and public credit infrastructure converges
Apollo has been explicit about the broader objective.
In June, the manager said it expected daily pricing eventually to become the norm in private credit, arguing that the infrastructure surrounding the asset class had not kept pace with its growth. Apollo pointed to its private-credit ETF as another example of efforts to combine private assets with the transparency and trading mechanisms associated with public markets.
For institutional investors, the implications extend beyond more frequent account statements.
Daily valuation data could improve portfolio risk monitoring, collateral analysis and comparisons between public and private credit. Standardized identifiers and greater secondary-market activity could also make private loans easier to analyze across managers.
For asset managers, however, the initiative raises the competitive bar. If large investors begin to expect daily portfolio marks, standardized asset data and better secondary-market information, other private-credit managers may face pressure to invest in comparable infrastructure.
That would represent a structural change for an asset class that historically benefited from accepting illiquidity and limited price discovery in exchange for potentially higher yields and customized financing terms.
Apollo’s $850 billion rollout does not make private credit a public market. It does, however, push one of the world’s largest credit platforms toward a model in which investors can see estimated values every business day rather than waiting for traditional monthly or quarterly valuation cycles.
That could make transparency itself an increasingly important point of competition among private-credit managers.