Private Credit Secondaries and GP-Led Deals Take Center Stage at SuperReturn New York

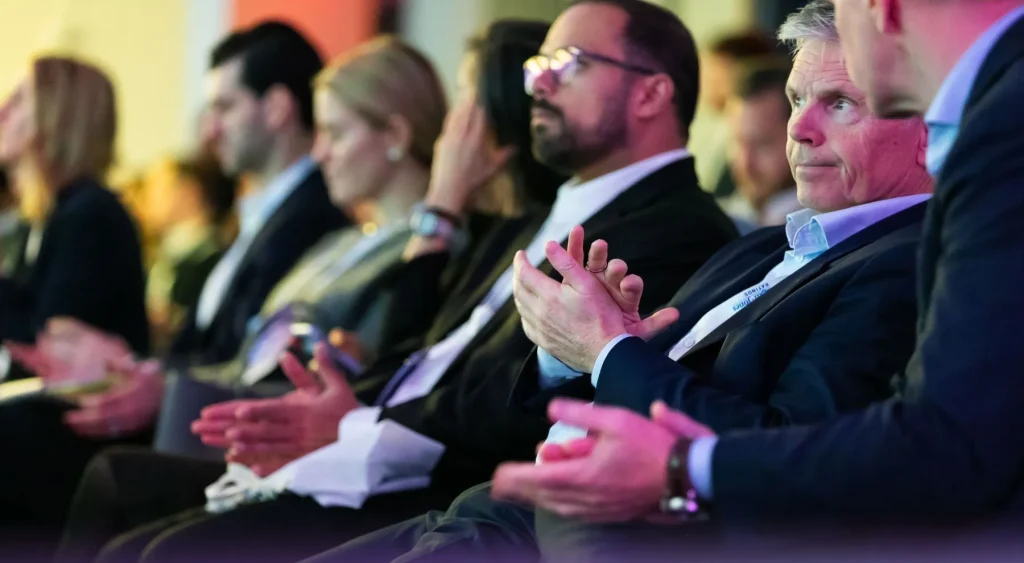
SuperReturn Secondaries North America 2026 brought private equity managers, institutional investors and secondary-market specialists together in New York on Nov. 17-18 to examine liquidity pressures, GP-led continuation vehicles, LP portfolio sales and the expansion of private credit secondaries.
Held at Convene, 360 Madison Avenue, the two-day conference focused on how investors can generate liquidity from long-held private assets while managing valuation uncertainty, transaction complexity and competing demands for capital.
Organized by Informa Connect, the event was designed for more than 250 senior secondary-market decision-makers, including over 100 limited partners and 100 general partners. Its agenda reflected a market in which secondaries have become an increasingly important portfolio-management tool rather than simply a mechanism for selling distressed or unwanted fund interests.
Institutional Investors Examine Liquidity and Portfolio Rebalancing
The conference opened with discussions about changing pricing conditions, institutional liquidity requirements and the development of North America’s secondary investment market.
According to the official SuperReturn Secondaries North America conference program, the agenda covered LP-led portfolio rebalancing, GP-led transactions, continuation vehicles and specialized secondary investment strategies.
Participants included representatives of institutional investors and asset managers such as CPP Investments, Adams Street Partners, Hamilton Lane, HarbourVest Partners and the New York State Common Retirement Fund.
For limited partners, secondary transactions provide an alternative to waiting for fund managers to sell portfolio companies and distribute proceeds.
Investors can use these transactions to reduce exposure to particular managers, rebalance vintage-year commitments, address liquidity requirements or redirect capital toward new opportunities.
However, selling an existing fund interest can involve a discount to reported net asset value, depending on portfolio quality, market demand and the terms of the transaction.
The conference’s focus on pricing and execution reflected the importance of these trade-offs in institutional portfolio management.
GP-Led Continuation Vehicles Attract Greater Attention
General partner-led secondaries were another central theme.
Continuation vehicles allow a private equity manager to transfer selected portfolio assets into a new investment structure, typically offering existing limited partners a choice between receiving liquidity and maintaining their investment exposure.
These arrangements can give managers additional time to develop portfolio companies without requiring an immediate sale to a strategic buyer or another financial sponsor.
They also introduce governance considerations because the same manager may influence both the sale of an asset from an existing fund and its acquisition by a new vehicle.
Valuation procedures, investor consent, transaction expenses and carried-interest arrangements are therefore important elements of institutional due diligence.
The conference included a session examining developments beyond the established single-asset continuation vehicle model.
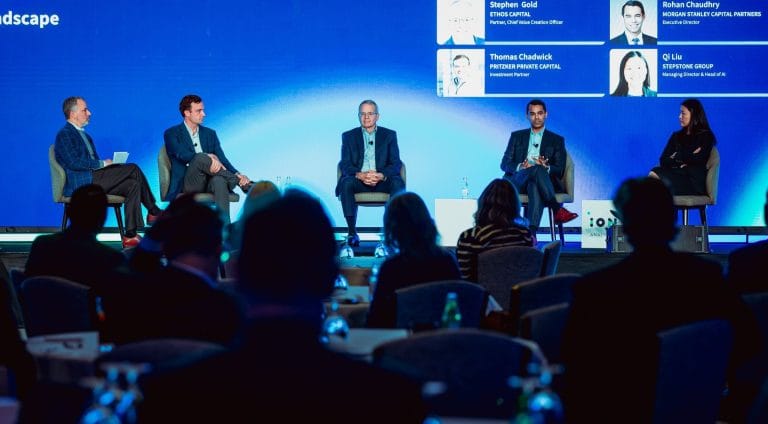
Lauren King, head of the secondaries practice at Simpson Thacher & Bartlett, moderated a discussion on the next phase of GP-led secondaries, including dedicated GP-led investment capital and evergreen structures.
The firm’s published account of its participation in SuperReturn Secondaries North America also identified private credit secondaries and the expansion of secondary investment products into private wealth as major conference subjects.
The governance issues surrounding these transactions have become increasingly relevant as continuation funds expand.
PE NEWSWIRE previously examined how private equity leaders are defending continuation funds amid growing investor scrutiny, including questions about valuation practices and conflicts of interest.
Private Credit Secondaries Expand the Liquidity Discussion
The conference also examined the development of secondary transactions beyond conventional private equity buyout funds.
Private credit secondaries allow investors to acquire existing interests in credit funds or portfolios of loans, creating potential liquidity for investors holding otherwise illiquid debt investments.
Unlike traditional buyout secondaries, private credit transactions require detailed consideration of borrower creditworthiness, loan documentation, collateral, repayment schedules and recovery assumptions.
The pricing of these portfolios may also be affected by interest rates, credit spreads and changes in borrower financial performance.
For institutional investors, secondary credit investments can offer access to seasoned portfolios with existing repayment histories.
However, the age of a loan portfolio does not necessarily imply lower risk. Credit deterioration, refinancing requirements and borrower concentration remain important considerations.
The growth of specialized secondaries strategies is also evident in fundraising activity.
The strategy illustrates how dedicated secondary managers are pursuing specific transaction sizes and portfolio characteristics rather than competing exclusively for large diversified fund portfolios.
Private Wealth and Evergreen Funds Create New Opportunities
Another major topic involved expanding secondary-market access beyond traditional institutional investors.
The conference examined how registered investment advisers, wealth managers and private investors are increasingly evaluating mature private-market portfolios.
Ryan Brizek, a registered funds partner at Simpson Thacher, participated in a Nov. 18 discussion about the use of secondary investment solutions within private wealth management.
Evergreen and semi-liquid structures are attracting interest because they can provide investors with periodic subscription opportunities and, subject to restrictions, redemption mechanisms.
However, the underlying investments remain relatively illiquid.
Fund managers must therefore manage the relationship between investor redemption expectations and the time required to sell private assets.
For secondary-market specialists, this creates opportunities to develop portfolios and investment structures suited to different investor groups.
For regulators and institutional allocators, the corresponding questions concern valuation transparency, liquidity management, investor suitability and fee disclosure.
Networking Remains Central to Secondary Transactions
Beyond formal conference sessions, SuperReturn emphasized direct interaction between limited partners, general partners and transaction advisers.
The program included closed-door LP/GP discussions, LP-only sessions, a women in secondaries networking lunch and dedicated meeting opportunities.
These formats are particularly relevant in secondary investing, where access to information, manager relationships and transaction execution capabilities can influence investment opportunities.
Secondary transactions frequently involve negotiated transfers of existing interests rather than standardized securities traded on public exchanges.
As a result, established relationships can support transaction sourcing and due diligence, although they do not replace independent valuation and risk assessment.
The event also reflected growing efforts to broaden professional networks within the secondary investment industry.
What SuperReturn Secondaries North America Means for Investors
The November conference highlighted several developments influencing institutional secondary-market investment.
LP-led transactions remain important for portfolio rebalancing and liquidity management, while GP-led continuation vehicles provide alternative ownership structures for assets requiring longer holding periods.
Private credit secondaries are broadening the range of underlying assets available to buyers, and evergreen investment structures are creating new distribution opportunities.
These developments also increase the complexity of investment selection.
Institutional investors must evaluate pricing, underlying portfolio quality, manager incentives, liquidity terms and potential conflicts of interest across increasingly specialized strategies.
The conference did not establish that particular investment structures will deliver superior returns, nor did its published materials provide a verified aggregate value of transactions completed during the event.
Its significance lies in the range of liquidity and portfolio-management challenges addressed by an increasingly specialized secondary investment industry.
For private equity managers and limited partners, the central question is no longer simply whether secondary markets can provide liquidity. It is how that liquidity can be structured, priced and delivered without compromising long-term investment outcomes.