Private Credit Leaders Confront Europe’s Crowded Lending Market at London Summit

European direct lenders are confronting a more competitive market as U.S. private credit firms expand across the region, banks selectively return to leveraged lending and growing pools of capital put pressure on spreads, sharpening the focus on origination, underwriting and portfolio construction.
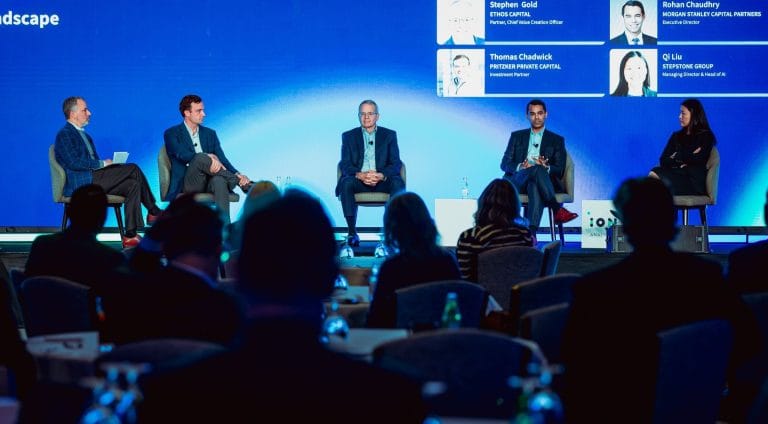
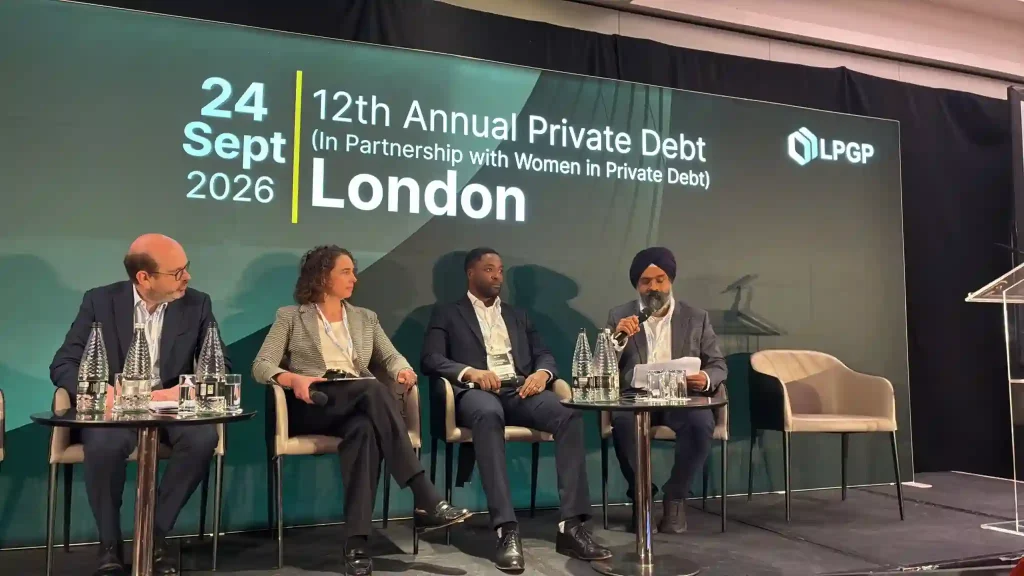
Those pressures were central to discussions at the 12th Annual LPGP Connect Private Debt London conference, held Sept. 24 at Park Plaza Victoria in partnership with Women in Private Debt. The event brought together senior private credit managers, institutional investors and advisers to examine capital deployment and the changing competitive position of private lenders. The organizer’s official conference program listed more than 40 speakers across eight panel sessions.
The debate comes despite strong headline deployment. European direct lending reached a record €63.16 billion ($73.6 billion) in the first half of 2026, according to Debtwire data previously reported by PE NEWSWIRE, but second-quarter volume declined as syndicated loans and high-yield bonds competed more effectively for larger borrowers.
PE NEWSWIRE’s analysis of record European private credit deployment found direct lenders completed €28.4 billion across 296 transactions during the second quarter, down 25% from €38.04 billion a year earlier.
US managers and banks increase competitive pressure
One of the conference’s central sessions framed European direct lending as being at an “inflection point,” examining competition, spread compression and where lenders can still differentiate.
The panel was moderated by Gurvinder Singh, CEO and co-founder of Indus Valley Partners, with participants including Sophia Alison of Macquarie Asset Management and Peter Jeranyama of Pension Insurance Corporation. Indus Valley Partners said the discussion would examine U.S. managers’ expansion into Europe, the selective return of banks, capital inflows, concentration risk and the growing prevalence of club and syndicated private-credit transactions.
Those forces are changing the economics of direct lending.
Private lenders expanded rapidly when banks retreated from leveraged and middle-market lending. That financing gap remains important, but stronger public credit markets and increased competition mean borrowers with sufficient scale now have more alternatives.
Large companies can increasingly compare direct loans against broadly syndicated loans and high-yield bonds, forcing private lenders to compete on execution certainty, documentation, flexibility and structural complexity rather than relying solely on the availability of capital.
European banks have not disappeared from private credit either. S&P Global Ratings estimated in May that seven major European banks had roughly €108 billion of direct lending exposure to private credit funds, equivalent to about 2% of their combined customer loans.
Middle market becomes a battleground
The competitive shift increases the importance of Europe’s middle market, where private lenders can retain advantages over broadly syndicated markets.
Smaller borrowers frequently require bespoke financing, have fewer viable public-market alternatives and may place greater value on certainty and speed. That can provide private credit managers with greater negotiating power than they have when financing large-cap companies able to run competitive processes involving banks, bond investors and direct lenders.
But more capital pursuing those transactions can itself weaken lender economics.
Managers must decide whether to accept tighter spreads and weaker protections to maintain deployment or remain selective and risk holding more undeployed capital. For limited partners, the distinction makes manager selection increasingly important: two funds nominally pursuing European direct lending can produce materially different portfolios depending on origination channels, borrower size, sponsor relationships and willingness to compete on price.
The conference discussion specifically highlighted sourcing, origination and portfolio construction as areas where managers can seek differentiation as competition increases.
Fundraising growth raises the underwriting stakes
Competition is occurring on both sides of the private credit business.
Managers are competing for attractive loans while simultaneously competing for institutional commitments. Pension funds, insurers, sovereign investors and other allocators now have a growing range of direct-lending, opportunistic credit, asset-backed and hybrid public-private strategies from which to choose.
That expansion is creating new distribution channels. PE NEWSWIRE previously reported on Capital Group and KKR’s public-private credit strategy for Europe and Asia, which combines roughly 60% public fixed income with 40% private credit managed by KKR.
For managers raising traditional institutional funds, however, abundant capital creates pressure to demonstrate that fundraising growth can be translated into attractive deployment without sacrificing credit standards.
The tension becomes more important when borrower financing costs remain elevated.
Floating-rate private loans have generated strong income for lenders during the higher-rate cycle, but the same rates increase interest burdens for portfolio companies. The result is a narrower margin for error when underwriting companies with high leverage or limited cash-flow cushions.
Europe’s record deployment masks a changing market
The headline numbers suggest European private credit remains in expansion mode.
Yet the composition of that activity provides a more nuanced picture. Refinancings represented about 37% of second-quarter direct-lending proceeds, while Europe’s leveraged-loan and high-yield markets generated approximately €128.3 billion of issuance during the quarter, according to Debtwire data previously reported by PE NEWSWIRE.
That means private lenders are operating in a market where capital deployment can remain historically high even while competitive advantages narrow.
For institutional investors, the resulting question is increasingly less about whether European private credit will continue growing and more about which managers can preserve attractive risk-adjusted returns as the market becomes crowded.
The London conference’s direct-lending debate captured that transition. U.S. managers are expanding, European lenders are defending established origination networks, banks are selectively competing for borrowers and public credit markets have reopened as an alternative for larger companies.
That environment does not eliminate the European private credit opportunity. It changes where the opportunity is likely to be found.
Middle-market origination, non-sponsored lending, complex financing and situations requiring bespoke structures could become more important sources of differentiation, while straightforward large-cap loans face greater pricing competition.
For private credit managers, Europe’s next phase may therefore be defined less by how much capital they can raise than by whether they can resist deploying it on increasingly borrower-friendly terms.